Claims Support
A roof claim only holds up if the documentation holds up first.
We are a commercial roofing contractor, not a public adjuster. We do not file claims, negotiate settlements, or represent owners in a dispute with a carrier. What we do is get on the roof before the estimate is written: we document the actual damage, the actual roof assembly, and the actual repair scope, so the owner and the adjuster are working from the same set of facts instead of a guess made from the ground.
What a usable claim file actually contains
A carrier wants more than a photo of a stained ceiling tile. Our field package typically includes dated photo logs of the roof surface and every penetration, moisture-meter or infrared readings where interior leaks suggest wet insulation, roof measurements tied to the affected area, and a written description that connects the damage to a specific event rather than general wear. Where the cause is unclear, we say so - a claim built on an overstated cause creates more problems later than it solves now.
Meeting the adjuster on the same roof
When the schedule allows, we walk the roof with the assigned adjuster directly. That single meeting does more than a written report can: both of us are looking at the same seam, the same parapet flashing, the same ponding area, at the same time, with our own photos and notes as reference. Disagreements about scope tend to shrink when they are settled on the deck instead of over email weeks later.
Framing a complete scope beyond the visible patch
A quick estimate written from a ground-level look almost always undercounts the job. Our scopes account for code and ordinance items a first pass tends to miss - current cover-board and insulation requirements, drainage corrections where a roof was already ponding before the loss, parapet and coping work tied into the damaged section, and material matching where a partial repair would otherwise leave a visibly mismatched membrane. Complete, in our estimates, means nothing legitimate gets left off the scope - not a bigger number for its own sake.
Building stock this comes up on most
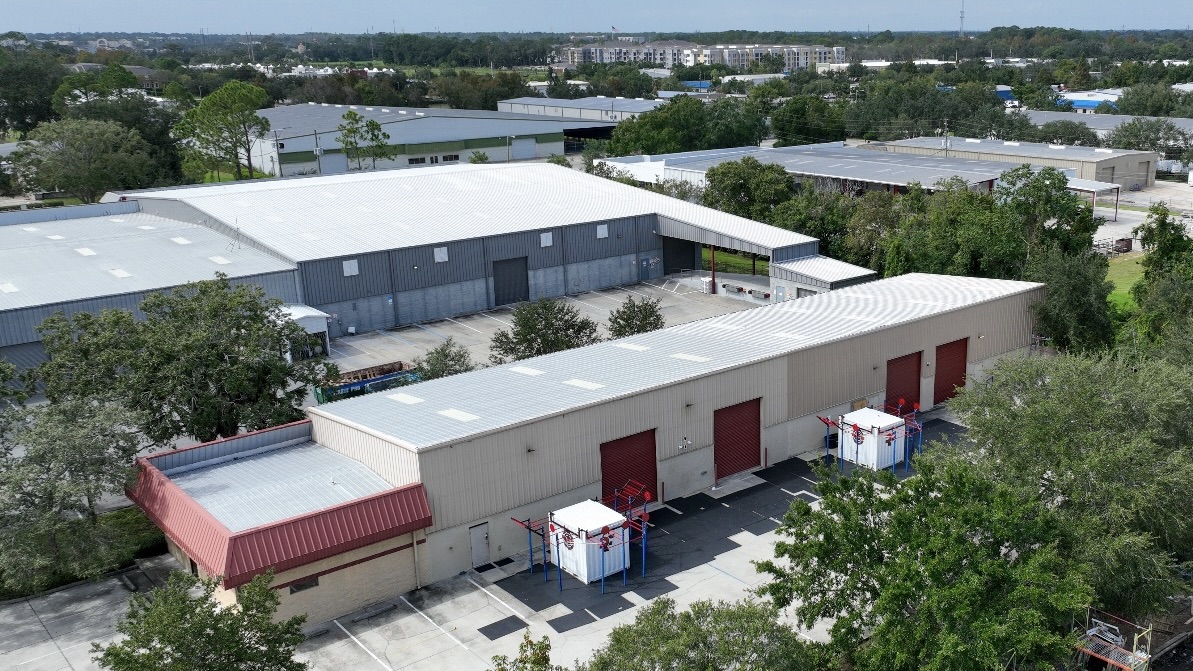
Oakland's commercial roof stock varies enough that no two claims look alike. Distribution and logistics buildings near the Port of Oakland carry large single-ply or coated membrane roofs where wind and ponding are the recurring issues. West Oakland's older industrial buildings often still run built-up asphalt roofing, sometimes with a later recover layer on top, and a claim there usually means tracing a leak through several roof generations at once. Downtown and Uptown adaptive-reuse buildings bring their own complication: a converted historic structure may have newer rooftop mechanical additions sitting on an older deck, with transition flashing that was never designed for the load or traffic it now gets.
The California property insurance market, in practical terms
Commercial property owners in California have felt carriers get more selective over the past several years, and roof condition is one of the first things underwriting looks at - both at renewal and after a loss. Some properties have moved toward surplus-lines coverage or seen higher scrutiny on roof age and prior repair history. None of that changes what we do: it makes a documented, current roof condition record more valuable to have on hand ahead of a renewal, before a loss ever happens.
When a claim comes back denied or underpaid
If a carrier denies a claim or the payout looks short of the actual repair cost, we can re-inspect the roof and point to specific conditions - a section of damage outside the original photo set, a code item left off the first scope, a measurement that undercounted the affected area. We hand that documentation to the owner or their broker. We do not argue the claim ourselves, and we do not promise a different outcome; carriers make the coverage decision.
If you manage a single building or a portfolio across the East Bay, the more useful move is calling before the next storm, not after. A roof with a current inspection on file gives everyone - owner, broker, and adjuster - a shared starting point instead of a rushed one.